Who this card is for
A good fit if you…
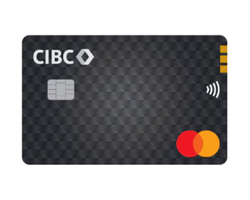
- Costco members who already fill up at the Costco gas bar and eat out often enough for a 3% restaurant rate to matter, and who will actually use this Mastercard at the till (Costco Canada does not take Visa).
- Households that order from Costco.ca and can keep that spend under the annual 2% cap described in the detailed features.
- People who want a $0-fee cobrand they can also hand to a partner — additional cards currently show $0, up to a small number of extras.
- Applicants who can meet the modest income figure in eligibility and will pay the statement in full. This is a cash-back card, not a cheap line of credit.
Skip it if you…
- Shoppers who are not Costco members and will not join. Eligibility currently says an active membership is required to apply.
- People whose Costco trip is the weekly grocery run and who expected 3–5% inside the warehouse. The card’s features pay 1% on those purchases.
- Anyone who wanted CIBC’s 4% supermarket Visa. That is Dividend Visa Infinite, which will not go through at Costco.
- Revolvers. The purchase rate will erase a year of Costco gas cash back in a cycle or two.
Pros and cons
Pros
- No annual fee, so you are not racing a $120 membership on top of the Costco membership you already pay.
- 3% cash back at restaurants and at Costco gas is a real commuting-and-dining pair if those are already habits.
- 2% at other gas stations, EV charging, and Costco.ca (each with an annual cap in the detailed features) covers the weeks you miss the warehouse pump or shop online.
- 1% on the warehouse floor and everywhere else still beats 0% — and Mastercard is the network Costco Canada actually accepts.
- The current welcome offer is a simple statement credit after a spend hurdle, not a points puzzle.
Cons
- You cannot apply without an active Costco membership. The card is a member perk, not a way to skip the membership desk.
- Warehouse grocery is 1%, not 3%. If Costco is your supermarket, a dedicated grocery card will usually beat this cobrand on food.
- The 2% gas/EV and Costco.ca rates currently reset on January 1 after listed annual caps. Blow past them and you are on 1%.
- Check the issuer’s site for current insurance coverage. Do not assume travel medical coverage from a CIBC Mastercard.
- Cash back is Costco/CIBC’s program, not Aventura or Aeroplan. It will not book a flight.
Fees and value: is the annual fee worth it?
First-year snapshot (estimate)
- Annual fee
- $0
- Estimated welcome bonus value
- $100
- Bonus minus fee (estimate)
- $100
This is a simple comparison of the estimated welcome-bonus value against the annual fee. It ignores rewards on spending, credits you have to remember to use, and interest if you carry a balance. Offers change — verify with the issuer.
This is a $0-fee card, so the first-year snapshot on this page is mostly the welcome statement credit minus nothing. Value after that is 3% Costco gas and restaurants, capped 2% on other fuel/EV and Costco.ca, and 1% in the warehouse.
Do not compare it with a 4–5% grocery Visa as if the warehouse paid the same rate — it does not. If you already pay for Costco, this Mastercard is the till card; put supermarket banners that are not Costco on a grocery earner.
Additional cards currently show no extra annual fee, up to the count in the detail line. Offers change.
Pay in full. Interest is not a Costco rebate.
Rewards and earn rates explained
Rewards program: Cash Back
You earn cash back, not points. The current stack in the card’s features is 3% at merchants classified as restaurants and as Costco gas stations in Canada; 2% at other gas merchants and EV charging (MCC 5552) on the first slice of annual net spend in that bucket, then 1%; 2% on Costco.ca on a separate annual cap, then 1%; and 1% on all other qualifying purchases, including inside Costco warehouses.
Those caps currently reset on January 1. Merchant coding still applies: a food court that processes as Costco retail, a restaurant inside a hotel, or a third-party “Costco” marketplace seller can miss 3% or 2%.
Redeem as cash back according to CIBC’s Costco program rules. If you want 4% at a regular grocer, compare Dividend Visa Infinite — and keep this Mastercard for the club, because that Visa will be declined at the warehouse.
Welcome bonus: how to unlock it
Join and earn a $100 Welcome Bonus!
The current offer is a $100 statement credit when you spend a listed amount within 120 days of account opening. Eligibility currently requires an active Costco membership to apply.
There is no first-year annual-fee rebate to stack because the fee is already $0. Hit the spend with warehouse trips, gas, and restaurants you would make anyway; do not add a second freezer you will not use.
Confirm the live CIBC/Costco page — membership status is the gate, not a CIBC chequing package.
Welcome bonus eligibility: An active Costco membership is required to apply for either card.
FAQ
Is the CIBC Costco Mastercard worth it in 2026?
It is worth it if you are already a Costco member, will use Mastercard at the warehouse and gas bar, and want 3% restaurants without an annual fee. It is not worth it as a 4% grocery substitute, and it is not available if you will not hold a Costco membership.
Do I need a Costco membership to apply?
Yes. The eligibility text currently says an active Costco membership is required to apply. The card does not replace the membership; it sits on top of one.
How much cash back do I earn inside the Costco warehouse?
The current features pay 1% on warehouse purchases, the same as the catch-all rate. The 3% rate is for Costco gas and for restaurants, not for the cart of groceries and paper towels. Costco.ca has its own 2% rate with an annual cap.
CIBC Costco Mastercard vs CIBC Dividend Visa Infinite?
Dividend Infinite is a paid Visa with a high grocery-and-gas cash-back rate and Visa Infinite income rules. It will not work at Costco Canada. Hold the Costco Mastercard for the club and gas bar; hold Dividend Infinite only if a regular supermarket bill clears that fee. They solve different tills.
Does this card charge foreign-exchange fees?
Most Canadian Mastercards add a foreign-conversion fee on foreign-currency purchases. This is a domestic warehouse cobrand, not a no-FX travel card. For overseas spend, compare Scotiabank Passport Visa Infinite, and confirm CIBC’s current FX rate in the agreement.
Compare related cards and guides
More Canadian credit card lists that match this product, plus a few cards people usually compare it with.
- CIBC Dividend Visa Infinite Card review · CIBC · $120 annual fee
- Tangerine Money-Back Credit Card review · Tangerine · $0 annual fee
- National Bank World Elite Mastercard review · National Bank · $150 annual fee