
1-card stack
The set-and-forget cash back stack (Canada)
This stack is for Canadians who pay the balance in full and want a fair cash return without tracking categories every week. Start with one strong no-fee card. Add a second only if one heavy category is left behind.
By Andrew Card details as of How we review cards
Who this stack is for
- You pay in full every month and keep spend moderate.
- You have used the same bank card for years and want a simple upgrade.
- You would rather see statement credits than learn a points program.
- You will carry at most one or two cards.
Spending profile
Everyday mix across groceries, gas, and bills — without heavy category optimization. Illustrative reference spend is around $2,000 a month; use your own statement, not that figure, when you compare.
Goals
- Roughly mid-single-digit cash back on the categories that matter, with a $0 annual fee when possible.
- Nothing to track beyond autopay.
- A clear answer to “am I leaving much on the table?”
Common friction
- Comparison pages that feel like ads.
- Points programs that can change value.
- Caps and rotating categories that feel like homework.
Recommended stack
Annual fees and earn text below are pulled from our live card catalog when this page was built. Confirm every figure on the full review and with the issuer before you apply.
Role: Primary everyday card
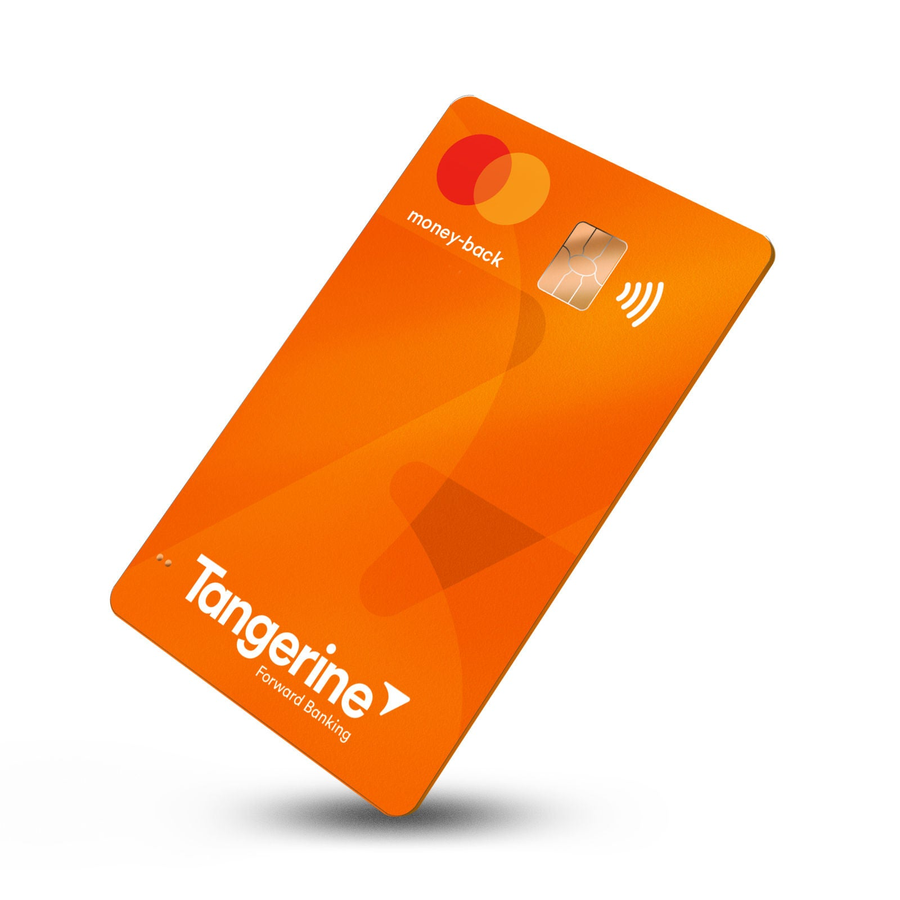
Tangerine Money-Back Credit Card
by Tangerine
- Annual fee
- $0
- Rewards program
- Cash Back
Earn (from our catalog): 2% cash back in up to 2 chosen categories (3 with a Tangerine savings account deposit of cash back); 0.5% on everything else.
Fit note: Pick the bonus categories that match your month. Confirm the live category list on the card page.
Role: Optional Amex cash-back card
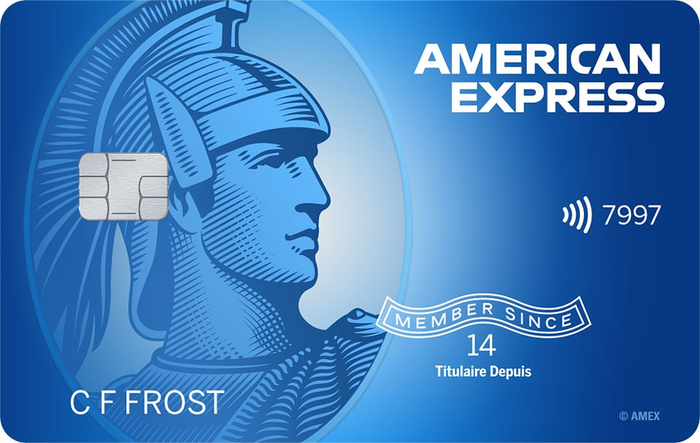
SimplyCash Card from American Express
by American Express
- Annual fee
- $0
- Rewards program
- Cash Back
Earn (from our catalog): 2% cash back on eligible gas station and grocery store purchases in Canada (up to $300 cash back a year). 1.25% cash back on all other purchases.
Fit note: 2% at stand-alone gas and grocery in Canada, up to $15,000 combined a year, then 1.25%. Keep a Visa or Mastercard backup.
Role: Optional Rogers-path everyday card
Rogers Red Mastercard
by Rogers Bank
- Annual fee
- $0
- Rewards program
- Cash Back
Earn (from our catalog): Earn 2% cash back on all eligible purchases with an eligible Rogers/Fido/Shaw/Comwave service (otherwise 2% on USD and 1% on other purchases), up to annual spend caps. 1.5x value when redeeming toward eligible Rogers-fam …
Fit note: Best when you already have an eligible Rogers, Fido, Shaw, or Comwave service. Confirm earn caps on the card page.
Alternatives and swaps
Use these when income, acceptance, or program preference blocks a recommended card.
Role: Rogers path with World Mastercard benefits
Rogers Red World Mastercard
by Rogers Bank
- Annual fee
- $0
- Rewards program
- Cash Back
Earn (from our catalog): Earn 2% cash back on all eligible purchases with an eligible Rogers/Fido/Shaw/Comwave service (otherwise 2% on USD and 1% on other purchases), up to annual spend caps. 1.5x redemption bonus toward eligible Rogers-family …
Fit note: Still $0 in our catalog — confirm current earn and caps on the card page.
When this stack is not for you
- You carry a revolving balance (interest usually wipes cash back).
- You want travel points, lounges, or insurance as the main payoff.
- You are willing to run three or four cards to maximize every category — see the category maximizer stack instead.
- You need a World Elite product for income-gated flat rates and do not mind the income test — compare Rogers Red World Elite on its own card page.
Related guides
Best No-Annual-Fee Credit Cards in Canada Right Now
Start with a $0 card that matches how you already shop. Tangerine, Simplii, Scene+, PC Optimum, and no-fee Amex cash back cover most Canadians who pay in full.
Read the guideBest Cash Back Credit Cards for Everyday Spending
Pay in full, then pick category cash back if two bills dominate, or a flat rate if spend is scattered. Points only win if you will redeem them like cash.
Read the guideRelated hubs and tools
FAQ
Do I need more than one cash-back card?
Usually no. One well-chosen $0 card covers most people in this persona. Add a second only when a single heavy category (for example dining on Amex, or Rogers bill redemption) clearly beats your primary card after you check live rates.
Is a no-fee card always better than a paid cash-back card?
Not always. A paid card can win if your grocery and bill spend clears the fee after you run the math on the live earn rates. If you will not track that math, stay on a $0 card.
Should newcomers start here?
If you already have a Canadian credit file and can get approved for a mainstream $0 rewards card, yes. If you are brand new to Canadian credit, start with the newcomer stack first.
Compare cards for your spend
Use the finder for a short list from the live catalog, then read each full card page before you apply.