Who this card is for
A good fit if you…
- Households whose largest bill is the supermarket, who want cash back in the same RBC app as their chequing account, and who do not want a $99-class World Elite fee.
- People who also shop wholesale and online — the detailed features currently fold those into the 1% “everything else” bucket, which still beats 0.5% no-fee Visas.
- Applicants who can park a listed amount of spend in the first three months to use the elevated welcome rate, during the offer window printed in eligibility.
- Anyone who pays in full. Two percent groceries will not outrun the purchase rate.
Skip it if you…
- Mixed spenders whose month is Costco, Amazon, and dining rather than grocery. Preferred World Elite currently lists a flat 1.5% on everything, which can beat 2% / 1% once the supermarket shrinks.
- Heavy grocery spenders who qualify for 4–5% supermarket cards. BMO CashBack World Elite and CIBC Dividend Visa Infinite advertise those percentages with narrower stacks and a fee.
- Shoppers who can pick two 2% categories at $0 and whose grocer is not the whole story. Tangerine will usually blend higher than 2% / 1%.
- Anyone who revolves a balance. One to two percent cash back is a rounding error next to the purchase rate.
Pros and cons
Pros
- No annual fee, with extra cards at $0, so 2% at the grocer does not have to beat a membership first.
- Up to 2% on grocery store purchases is a higher supermarket rate than Preferred World Elite’s flat 1.5% in that review.
- Up to 1% on other everyday purchases, including favourite online and wholesale retailers in the detailed feature list, is a usable Costco-and-Amazon catch-all on a Mastercard.
- The current welcome path pays an extra cash-back rate on a capped slice of first-three-months spend — a simple cash bonus, not a points estimate.
- No World Elite income test in the eligibility text. This is the accessible RBC cash-back Mastercard.
Cons
- “Up to” 2% and “up to” 1% in the features line is the issuer’s wording. Confirm the live rate on RBC’s page rather than assuming every grocer MCC pays the ceiling.
- Outside grocery, you are on 1%. Dining, gas, and bills do not get a second bonus category the way Tangerine and Dividend make you pick or stack.
- Welcome eligibility currently names a dated application window. Offers expire; do not treat that three-month 7%-class headline as a permanent product feature.
- The welcome-value estimate restates the 7% headline instead of a dollar wrap, so the first-year snapshot may not show a clean bonus-minus-fee figure.
- Check the issuer’s site for current insurance coverage. This is a $0 cash-back Mastercard, not a travel-medical product.
Fees and value: is the annual fee worth it?
First-year snapshot (estimate)
- Annual fee
- $0
- Estimated welcome bonus value
- up to $100
- Bonus minus fee (estimate)
- $100
This is a simple comparison of the estimated welcome-bonus value against the annual fee. It ignores rewards on spending, credits you have to remember to use, and interest if you carry a balance. Offers change — verify with the issuer.
This is a $0-fee card, with extra cards at $0, so the usual “bonus minus annual fee” snapshot on this page will look empty or unhelpful on the fee side. Value is 2% on grocery store purchases plus 1% on everything else, plus whatever the current three-month welcome window still pays if you apply inside the dates.
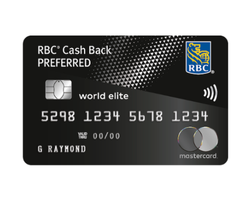
If the supermarket is the statement, this card can beat Preferred World Elite’s 1.5% minus $99. If the month is Costco, Amazon, and dining that would have paid 1% here, Preferred’s flat 1.5% can clear its fee.
If two Tangerine categories would cover more of the month, Tangerine wins at the same $0. There is no first-year fee rebate to hide a weak fit.
Offers change. Pay in full.
Rewards and earn rates explained
Rewards program: Cash Back
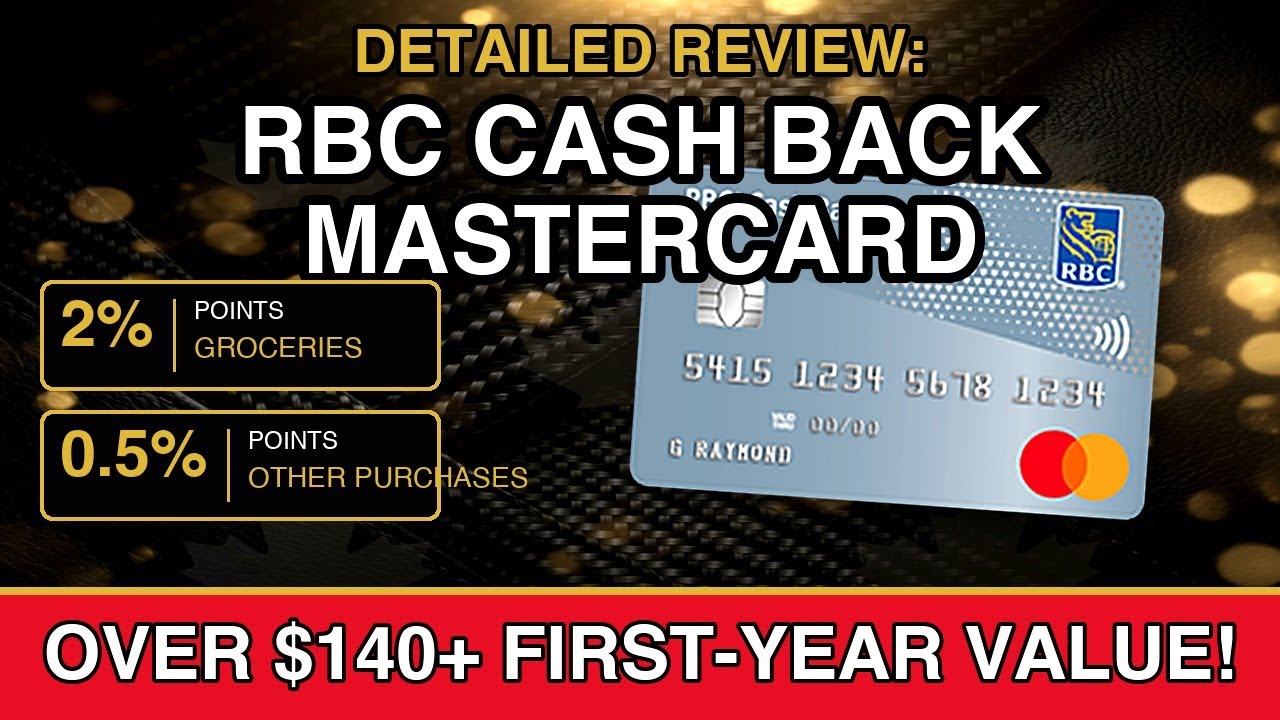
This card pays cash back, not Avion and not WestJet points. The current features describe up to 2% cash back on grocery store purchases and up to 1% on all other everyday purchases.
The detailed feature list currently adds that the 1% bucket includes favourite online and wholesale retailers — useful at Costco Canada, which takes Mastercard. There is no 3% dining line and no 5% grocery World Elite stack; those live on other issuers, or on RBC’s paid Preferred card as a flat 1.5%.
Merchant coding still matters: a warehouse club that codes as wholesale may miss 2%, a restaurant inside a grocer usually misses it, and a meal kit can miss it. Redeem as cash back according to RBC’s rules.
If you want pick-your-categories 2% at $0, that is Tangerine. If you want a single 1.5% rate on the whole statement and you can pass World Elite income, that is Preferred.
Welcome bonus: how to unlock it
Get 5% extra cash back on your first $2,000 in spend for 6 months (up to $100)
The current offer is an extra cash-back amount on net purchases in the first three months, up to a listed spend cap, marketed together with the regular grocery rate as a 7%-class window. Spend over that cap in those three months reverts to the regular 2% / 1% rates.
Eligibility currently limits the offer to new applications received inside a dated window printed — that window will go stale, so confirm on RBC’s page rather than assuming this review’s month is still live. Hit the cap with grocery you would buy anyway.
There is no separate first-purchase lump sum; the welcome is the elevated rate.
Welcome bonus eligibility: This offer only applies to new applications for an RBC Cash Back Mastercard credit card received between October 1, 2026 and February 2, 2027 and approved by Royal Bank. Additional cardholders (co-applicant and authorized users), and existing RBC personal credit cardholders transferring to an RBC Cash Back Mastercard during the Offer Period, are not eligible.
FAQ
Is the RBC Cash Back Mastercard worth it in 2026?
It is worth it when grocery is the story, you want RBC cash back at $0, and you pay in full. It is not worth it as a 1.5% catch-all, a 5% grocery substitute, or a card you revolve.
RBC Cash Back vs RBC Cash Back Preferred World Elite?
Preferred World Elite currently lists a $99-class fee and a flat 1.5% on all spending, with World Elite income. This card currently lists $0, up to 2% at grocery stores, and up to 1% elsewhere. Choose this $0 card if the supermarket is the bill. Choose Preferred if the rest of the statement is large and you qualify.
RBC Cash Back vs Tangerine Money-Back?
Tangerine lets you pick 2% categories at $0. RBC locks 2% to grocery stores and pays 1% elsewhere. Choose Tangerine if you want control and a second 2% bucket. Choose RBC if you already bank there and the grocer is the month.
RBC Cash Back vs Simplii Financial Cash Back Visa?
Simplii is another $0 cash-back Visa with its own earn mix in that review. This RBC card is a Mastercard, which matters at Costco Canada. Choose the bank you already use, then compare live grocery rates and whether you need Mastercard at the warehouse.
Does this card charge foreign-exchange fees?
Most Canadian no-fee Mastercards add a foreign-conversion fee on foreign-currency purchases. This is a domestic cash-back card, not a no-FX Passport. For overseas spend, compare Scotiabank Passport Visa Infinite, and confirm RBC’s current FX rate in the agreement.
Compare related cards and guides
More Canadian credit card lists that match this product, plus a few cards people usually compare it with.
- RBC Cash Back Preferred World Elite Mastercard review · RBC · $99 annual fee
- Tangerine Money-Back Credit Card review · Tangerine · $0 annual fee
- Simplii Financial Cash Back Visa review · Simplii Financial · $0 annual fee